RSI 2 Strategy for Trading Short-Term Pullbacks
A two-period lookback turns the classic RSI indicator into something absolutely different. In this case, the RSI can bounce off the walls from 0 to 100 in a few sessions, and it almost never stays in the middle ground. That's the purpose of it precisely. The 2 period RSI is not supposed to hunt for overbought areas. Its purpose is spotting a brief pullback inside a trend that continues. There is a difference between the purposes of such trading styles, hence between optimal lookbacks and exits. This guide introduces the basic principles of this method, two sample trades, reasons to ignore signals, and the effect of fees on ultra-frequent trading.
What Is the RSI 2 Strategy?
In essence, it’s a short-term mean-reversion strategy that Larry Connors used in research papers on rapid trading strategies. The system suggests entering a trend-following trade after the price drops sharply in a certain trend. A long-term filter indicates whether a trend exists, while a short-term oversold condition serves as an entrance criterion.
Notably, the system does not evaluate the overall level of the price. Instead, it analyses the occurrence of rapid decline amid the uptrend, whatever the degree of overboughtness.
One terminology issue is worth clearing up immediately. When you hear of the Connors RSI 2 strategy, this is the two-period RSI approach discussed in this article. ConnorsRS causes frequent misunderstanding here, though. It’s a different indicator by the same author. General RSI concepts and divergence trading are explained elsewhere, in this guide to bullish and bearish divergence and how to use RSI signals on charts.
One caveat. A value of 2 or 3 does not mean that a rebound is going to happen. It just means that the last two periods have been dominated by declining prices. It may stay that way for an indefinite period of downtrend.
RSI 2 Settings and Baseline Rules
Three parameters, all of them applied to daily candles. Any deviation from them results in a different strategy requiring testing.
Two-Period RSI Using Closing Prices
RSI with a two-period lookback that relies on closing prices only as its inputs. Intraday highs and lows are not used in the calculation, and so the signal cannot be generated until the session close.
Traditional 30/70 lines do not serve well as thresholds in this case. Due to the nature of the 2 period RSI strategy and its parameters, the crossing of such levels occurs too frequently. The thresholds drift to the extremes: below 5 for a long signal and above 95 for a short signal. Some traders prefer 10 and 90 instead, and that is a genuine trade-off rather than an improvement.
The 200-Day SMA Trend Filter
A 200-day simple moving average defines the direction of trades you are allowed to consider. The price has to close above it for long setups and below it for short ones.
This is the key component. Without it, a two-period oversold situation can arise just as easily within a prolonged downtrend as within a brief pullback.
The Five-Day SMA Exit Reference
Exit a long trade in case price closes higher than its own five-day simple moving average. Exit a short trade whenever the opposite thing occurs. That is your conditional exit strategy, not a predetermined one. It might take effect already tomorrow or up to eight days away after today.
What is particularly worth noting is what is left out of the usual rule, although it is easy to overlook. The absence of a stop-loss is typical of this particular system, and the reason is quite evident. Neither a target nor a stop-loss exists here; you stay engaged until the moving average condition is met.
Strategy Rules Table
Element | Baseline setting |
|---|---|
Timeframe | Daily candles |
Indicator | RSI, 2-period, closes only |
Trend filter | 200-day simple moving average |
Long setup | Close above the 200-day SMA |
Long entry | RSI(2) closes below 5 |
Long exit | Close above the 5-day SMA |
Short setup | Close below the 200-day SMA |
Short entry | RSI(2) closes above 95 |
Short exit | Close below the 5-day SMA |
Execution | Next session's open after the signal candle close |
Stop loss | None in the classical approach |
Open a live chart
Get StartedLong Entry and Exit Rules
One by one, without leaving anything to interpretation.
The session has to close above the 200-day SMA. Otherwise there is no long setup, regardless of the RSI reading.
RSI(2) has to close below 5. The close is what counts, so a fall below 5 during the session that recovers by the end does not trigger a signal.
Enter the position at the next session open. Since the completed candle signal appears after the close, the earliest possible execution is at the next session open.
Keep the position open without a stop, according to the classical rules. If you decide to add one, you will be testing a variant.
Exit the position on the condition of a close above the 5-day SMA, also at the next session open.
The third rule brings a cost worth remembering: next-session execution implies that once you see a signal and execute a trade according to the setup, you hold the position from the opening minute up until the next session starts. If the data you trade off is daily, you incur the overnight gap risk , whose significance will accumulate with each following transaction.
The Short-Side RSI 2 Variant
The structure is exactly the same. The price has to close below the 200-day SMA, RSI(2) has to close above 95, enter short at the next session open, and exit when the close is below the 5-day SMA.
The rules are symmetric, outcomes are not. It means that upward swings and downward swings don't look alike. Moreover, short side mean reversion strategies have a separate history of results. Don't try and deduce one from another.
Worked RSI 2 Trade Examples
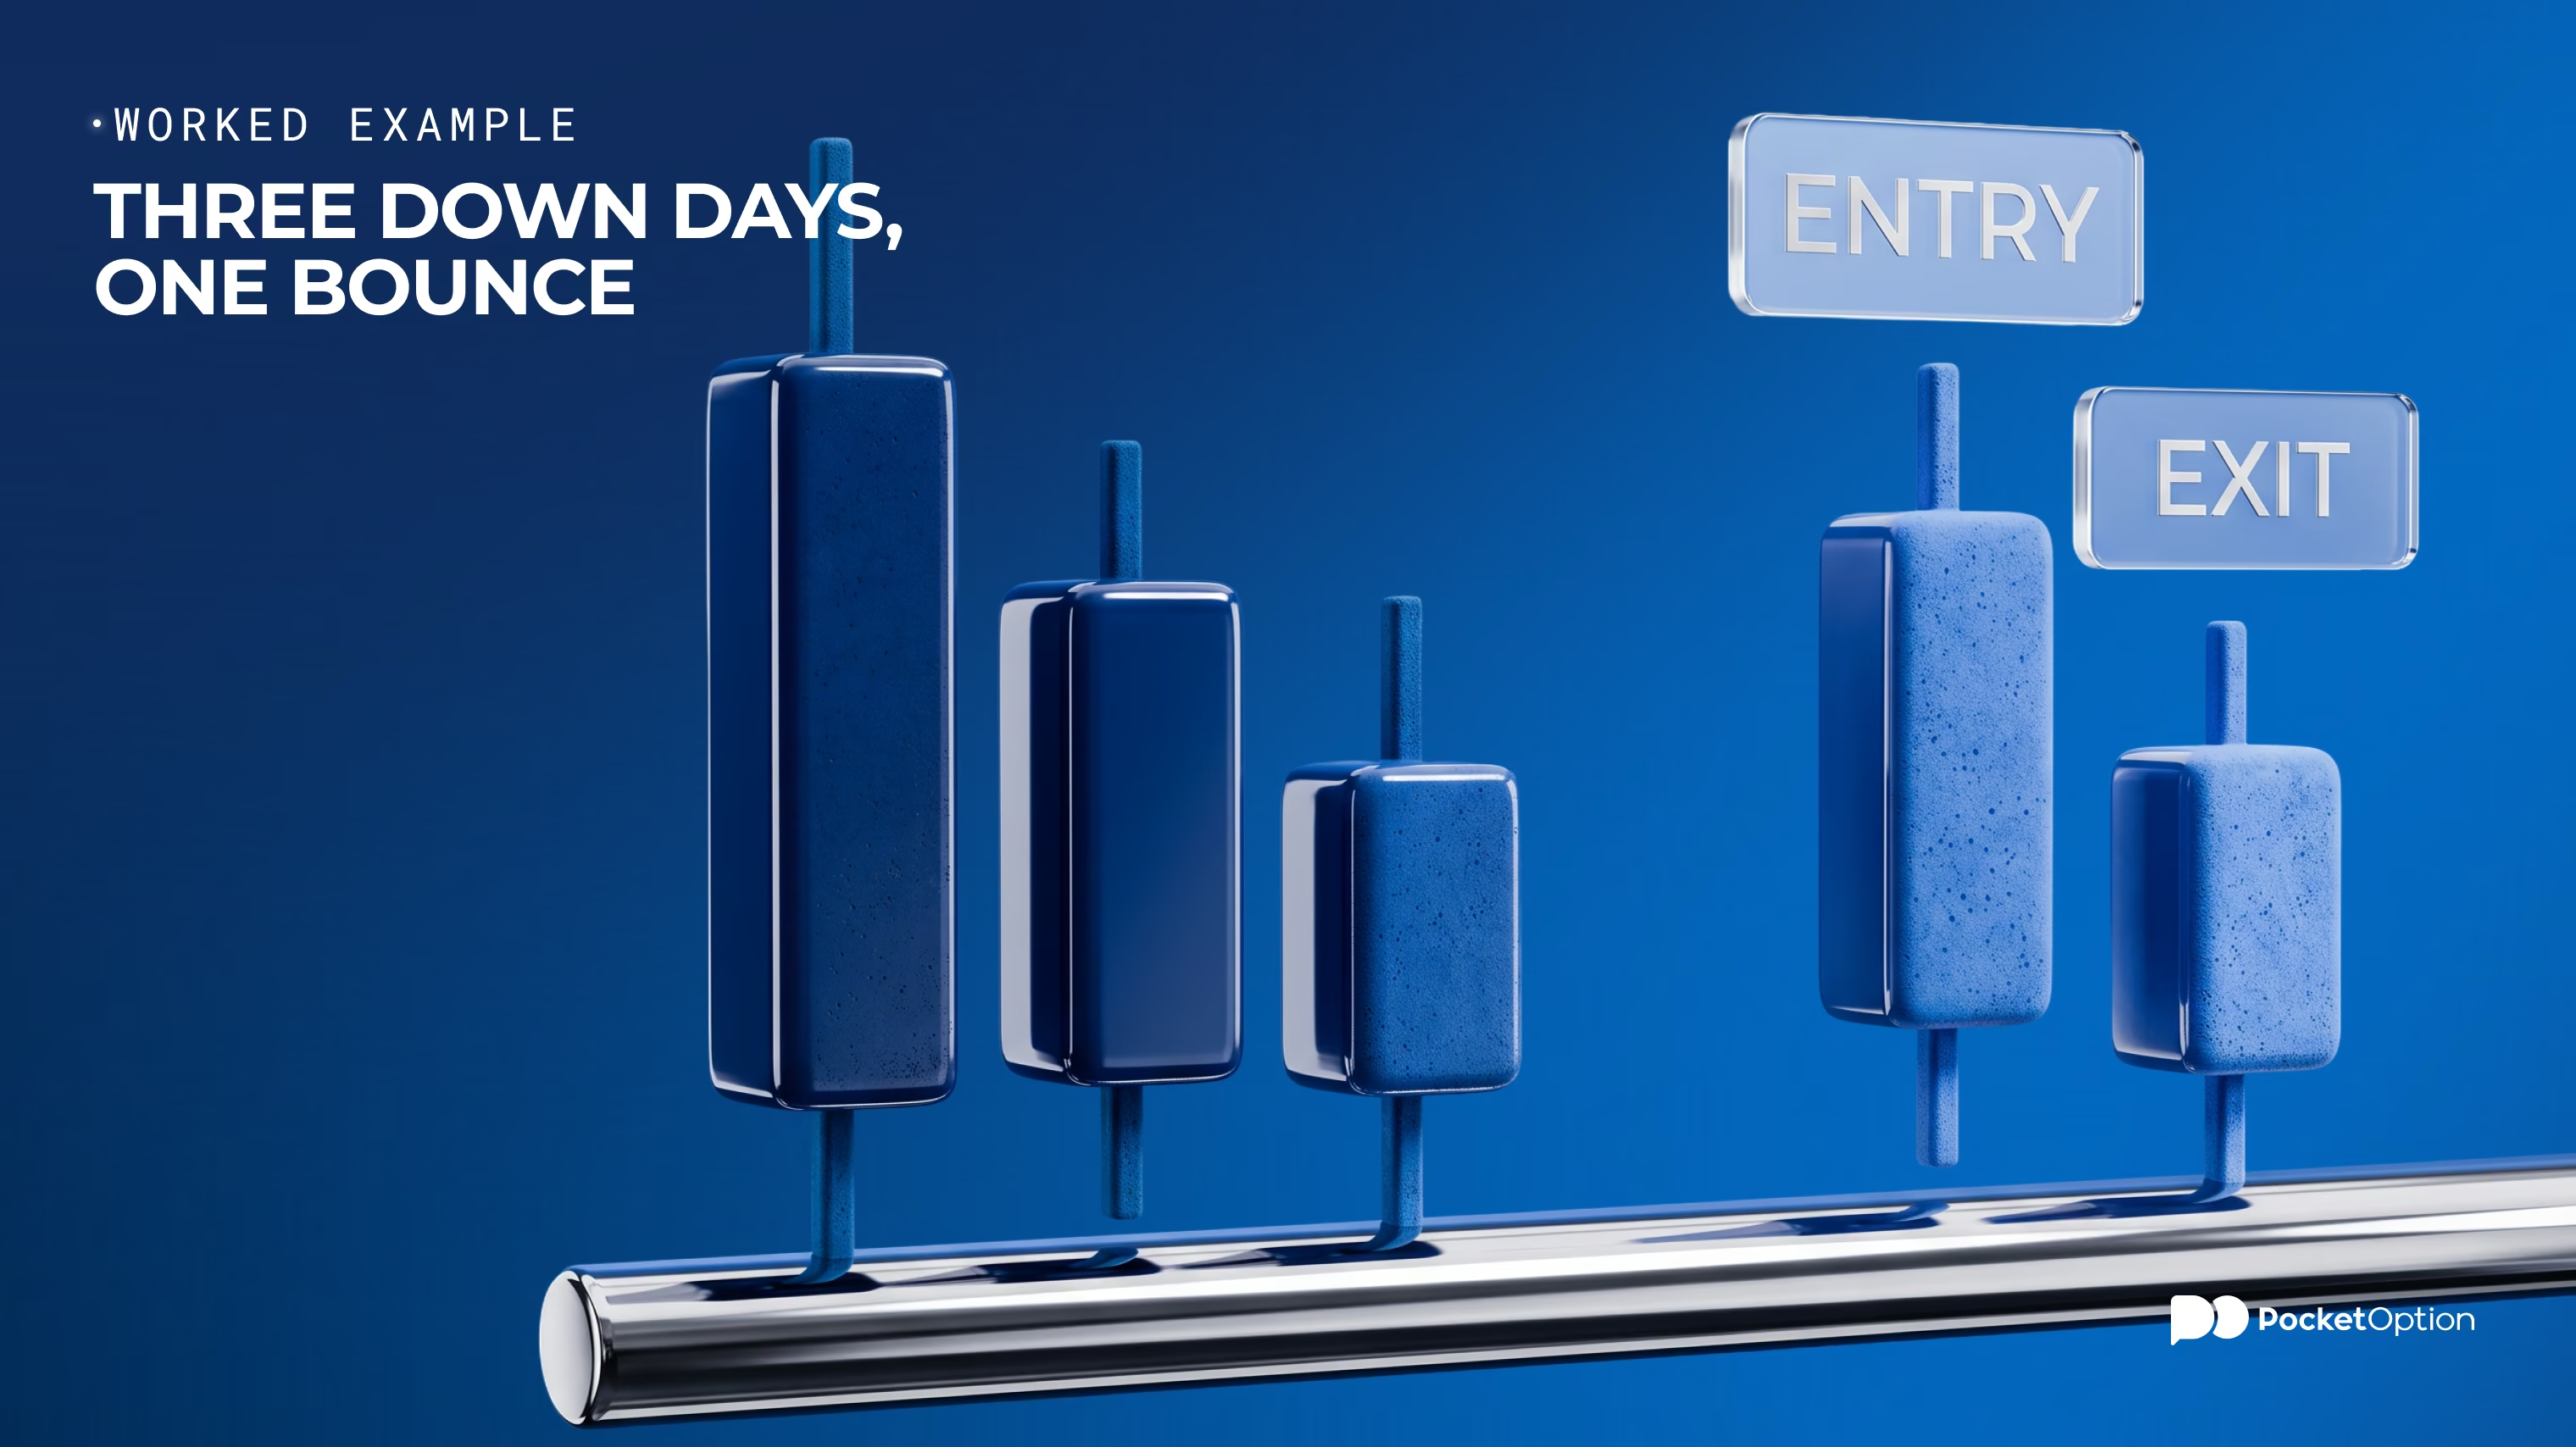
These are two hypothetical examples on the index asset, using arbitrary figures just for demonstration purposes.
Long Trade Setup and Execution. The 200-day SMA is 4,480, and the price is at 4,620. As the price exceeds the SMA line by a reasonable safety margin, long setups are enabled. The price declines during the next three sessions, closing at 4,575, 4,540, and finally at 4,508. All three levels remain above the filter. At the closing of the third session, RSI(2)=3.4, which crosses under the lower level. Open the position on the following session open at 4,512 with a four-point gap against the signal candlestick closing level. In three subsequent sessions, the price will close at 4,571 with the 5-day SMA crossing at 4,548. Execute the take profit order at the opening of the session with a resulting profit equal to 63 points, which is 1.40%. Without the slippage.
Short Trade Setup and Execution. The second scenario repeats everything from the previous example, except now it concerns a price lower than the SMA, therefore enabling a short trading opportunity. RSI(2)=96.8 on the third session closing with a 5-day SMA standing at 4,381. The price opened below the lower filter at 4,414 in response. After two more sessions, it closed below 5-day SMA at 4,361, thus executing the trade at a 56-point difference or 1.28%.
Summary: As it is seen, the holding time here varies between 2 to 3 trading days. This accounts for a relatively high frequency of trades created. Besides, note that neither of these gross profits looks particularly impressive, and therefore any trading cost becomes significant.
When to Skip an RSI 2 Signal
A signal that satisfies the rules is not necessarily a good trade to take. Consider skipping the signal in these situations:
There is an important scheduled event within the hold window. Earnings, or a significant policy decision for an index, may cause the price to move for reasons that cannot be accounted for by the strategy.
The filter is flat, and the price oscillates around it. If the 200-day SMA is sideways and the price crosses it multiple times, the direction rule stops making sense.
A news-driven price crash, not usual noise. Mean reversion assumes that the drop was noise, not a move based on new information.
A wide spread relative to the expected move. If round-trip costs amount to a significant part of the expected 1% move, the math is already failing.
There is an open position on a correlated instrument. Two index trades moving in the same direction are not two separate trades, but rather one position doubled in size.
Write down all of this before you trade. Avoiding signals based on your feeling afterwards is the silent road towards turning a tested strategy into an untested one.
Position Sizing and Risk Handling
The original rules lack a stop loss, relying entirely on the position size to manage the risk on an individual trade.
Fix the position size as a constant fraction of the account balance, determined beforehand and kept the same across all trades.
Anticipate that the worst-case scenario may turn out larger than the examples above. With no stop, the potential loss can be equal to the distance traveled by the price before the 5-day SMA condition is satisfied.
Calculate the maximum drawdown in testing, in addition to return. High-frequency trading with no stop may result in prolonged losing streaks.
If you add a stop or a time limit, test that version separately. It changes the exit distribution and everything else downstream.
Putting this into a written process, rather than making decisions on the spot, is covered in this guide to building a realistic trading plan.
RSI 2 vs ConnorsRSI
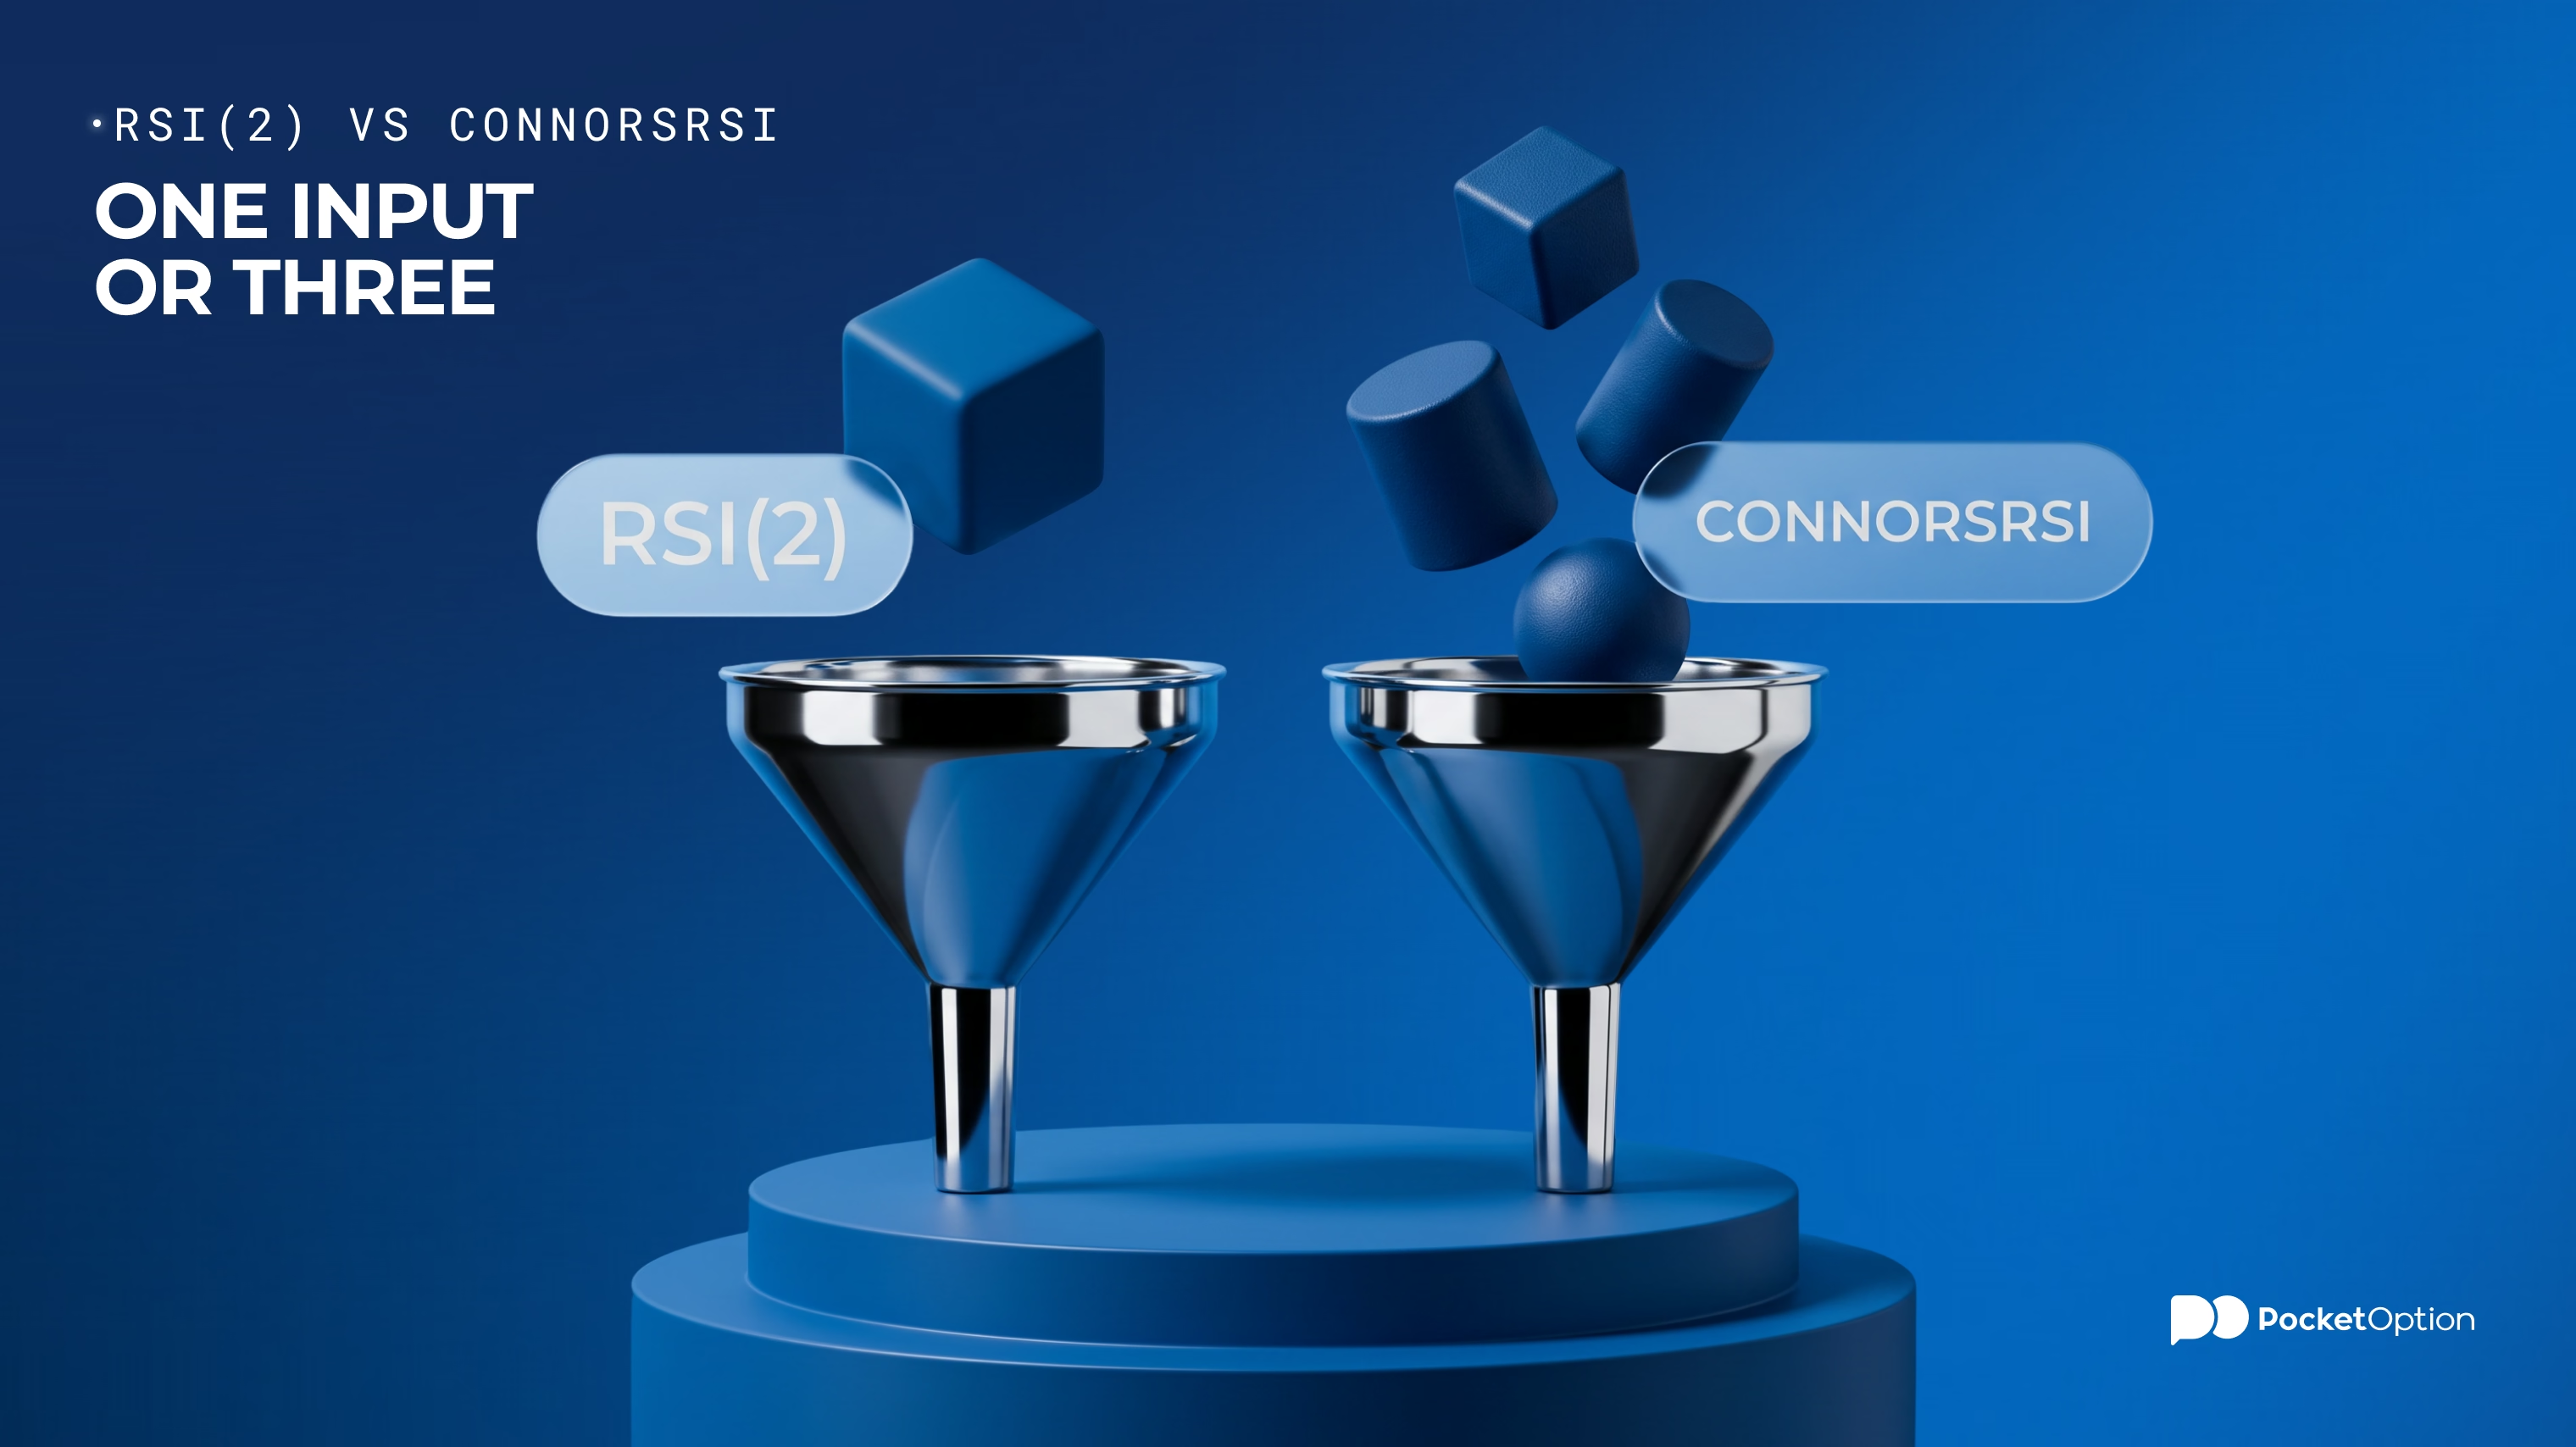
The ConnorsRSI vs RSI(2) question deserves to be clarified, because their similarity in names implies a relationship that does not exist between them.
RSI(2) is a basic Relative Strength Index with a two-period lookback, derived from a single data series.
ConnorsRSI is a composite indicator that came later, consisting of three equal parts: an RSI of price (typically 3 periods), an RSI of the up or down streak length (typically 2 periods), and the percentile rank of the last one-day change against a longer lookback (typically 100 days).
So they share an author and nothing else. You cannot apply a rule written for one indicator to the other simply by replacing the indicators, because their scales, their distributions and the meaning of an extreme reading all differ. The RSI2 strategy described in this article uses only RSI(2) throughout.
How to Backtest the RSI 2 Strategy
This system is simple enough that most of the difficulty comes from testing mistakes rather than from the rules.
Generate the signal only on completed candles. Since RSI(2) based on closing prices cannot be calculated intraday, entering on the signal candle is already an information leak.
Enter and exit at the next session open, and take the gap into account. This is the largest discrepancy between a neat backtest and a tradable system.
Deduct costs per trade. Include any trading commissions, as well as the spread and slippage, applied to both entry and exit, not just once.
Evaluate maximum drawdown and the number of trades, in addition to return. High frequency with a small average profit is a very cost-sensitive combination.
Set aside some period of data and test on it last, after all the rules are finalized.
Costs require arithmetic, not a warning. If the average gross profit per trade is 0.8% and round-trip costs are 0.1%, then this reduces the gross edge by 12.5% to 0.7%. It takes only small adjustments for everything to disappear. This is why a strategy that keeps positions for two or three sessions must be tested with costs deducted, and not adjusted afterwards.
Switching the timeframe is not a simple tweak of the strategy either. The rules applied to hourly or five-minute bars create a completely different variant of the system with its own statistics, and the test results for the daily variant do not give you any information about it. The general method is covered in this guide to backtesting trading strategies and turning raw ideas into tested plans.
Try a demo account
Try DemoTesting an RSI 2 Adaptation on Pocket Option Demo
An important thing to bear in mind is always the limit, inherent in every strategy, no matter how good.
The exit condition is simple enough: one waits for a move to breach the opposite side of a five-day simple moving average from closing price. Both moves described above ended up taking three days in the first instance and two days in the latter. A trade with fixed expiration date doesn't have a conditional exit, since the trade automatically expires at a predetermined point of time regardless of price behavior. Thus, this modification cannot be simply implemented without further tests.
Adaptation implies using a predefined period instead of a conditional exit, turning this into another strategy altogether, requiring separate analysis and testing. One significant distinction between those approaches is that a fixed payoff doesn't take into account the actual extent of movement, and a conditional exit does. With the latter option, the size of a move makes sense for calculating profits and losses; with the former one, the direction counts and that is all.
Thus, while evaluating any adaptation on demo, one must consider both parameters: the payoff shows required win rate percentage, allowing estimating breakeven level. Demo performance does not ensure success in real-life transactions; moreover, demo data cannot prove any edge at all.
Conclusion
There are plenty of ways why this approach is attractive, but let us mention clarity as the primary reason for preference here. Everything has been stated straightforwardly, with no hidden parameters left.
So test it on its own terms: generate the signal based on closing prices, execute at the next open, and account for the gap. Let the 200-day filter define the direction and regard the thresholds as deliberate choices you can defend. Remember that the classical version lacks a stop, which means the position size is the only protection against an adverse move. Track the maximum drawdown rather than the return, and remember that a value of 3 describes only the last two sessions, never the next move.
Disclaimer: This article provides purely informative commentary. The usage of the suggested trading approach is up to you. The values used here have been selected exclusively for demonstration purposes. There is absolutely no way of implying that the same price levels would lead to real deals on live markets. Neither can the provided numbers be used to validate any performance claims. Any historical performance data concerns testing results of the described model on the dataset. None of the thresholds or parameters ensure the occurrence of reversal. All strategies carry significant risks, particularly of losses.
See more:InterestingTrading Strategies