Accrual Accounting: What the Accrual Basis Is, How It Works and Why It Matters
A company can show positive results for a quarter despite negative cash flow. No fraud occurred, no one misreported and auditors will confirm that. That is how the system works. Understanding this difference is the most valuable insight when analyzing financial statements. The article explains the origins of this difference, follows a transaction through it, and presents a test of whether reported profit is supported by cash.

What Is Accrual Basis Accounting
In one sentence, what is accrual? It means accounting for the transaction at the moment of occurrence of the economic event, not at the moment of money exchange.
This is the essence of the matter. Under the accrual basis of accounting, you recognize revenues upon earning them and expenses at incurring them. The bank balance is a separate matter, presented in a different report.
Thus, the accrual meaning in accounting is concerned with timing, not amount. Over the entire lifetime of the business, both methods result in the same totals because every revenue will eventually either be received or written off. The difference is the moment of recording the transactions. Since you analyze a company's performance on the quarterly basis, the difference in timing is relevant.
The other option is cash basis accounting, which means that nothing is accounted until the cash exchange occurs. It is much simpler than accrual basis accounting and more often applied by small businesses, but not by publicly held companies.
The Two Core Principles: Revenue Recognition and Matching
Two main principles guide the whole system, and most of the surprising points in financial statements are connected to one of them.
Revenue recognition means recognition of revenue at the moment of fulfillment of obligations to the counterparty. Signing the contract or receiving payment does not count; the question is whether you have performed.
Matching means recognition of expenses in the same quarter that generated the revenue. Spending money in March to generate revenue in June means that you should recognize the expense in June, not in March when the payment was made.
Matching creates an accrued expense: a cost that has been incurred but not yet paid. Salaries for the staff who worked the last week of December are earned in December and paid in January, so December recognizes the expense and the balance sheet carries the liability until the payment is made. This is the accruals definition most people rely on.
The accrual concept illustrates the activities of the business in the period, not its cash inflows and outflows, and that is more informative for comparison than a snapshot of the bank account.
How Accrual Accounting Works in Practice
Accrual accounting needs locations to store the timing differences between occurrence of the event and the payment of it. There are several balance sheet items to account for these differences.
Accounts receivable: Revenue is recognized, but not yet received. The customer owes the company, and the profit is accounted as a paper one until the payment is made.
Accounts payable: Expenses are recognized, but not yet paid. The company owes someone.
Accrued expenses: Expenses occurred, but not yet invoiced, such as salaries, interest, utilities, or taxes in respect of a finished period.
Deferred revenue: Cash is received, but not yet recognized as revenue, so cash in the bank is a liability until the company fulfills its obligations.
Prepaid expenses: Cash paid in advance for something to use later, kept on the balance sheet as an asset and recognized as an expense gradually.
These five items are where accruals in accounting are held. To find out if profit is backed by cash, these accounts will help you, and their movements will be more important than balances.
Deferred revenue deserves special attention because it can work in favor of the trader. A software company receiving annually-paid subscription fees upfront has cash in the bank, but cannot report these revenues yet. Cash flow is ahead of the reported profit, not vice versa.
A Worked Example: Profit Before the Cash Arrives
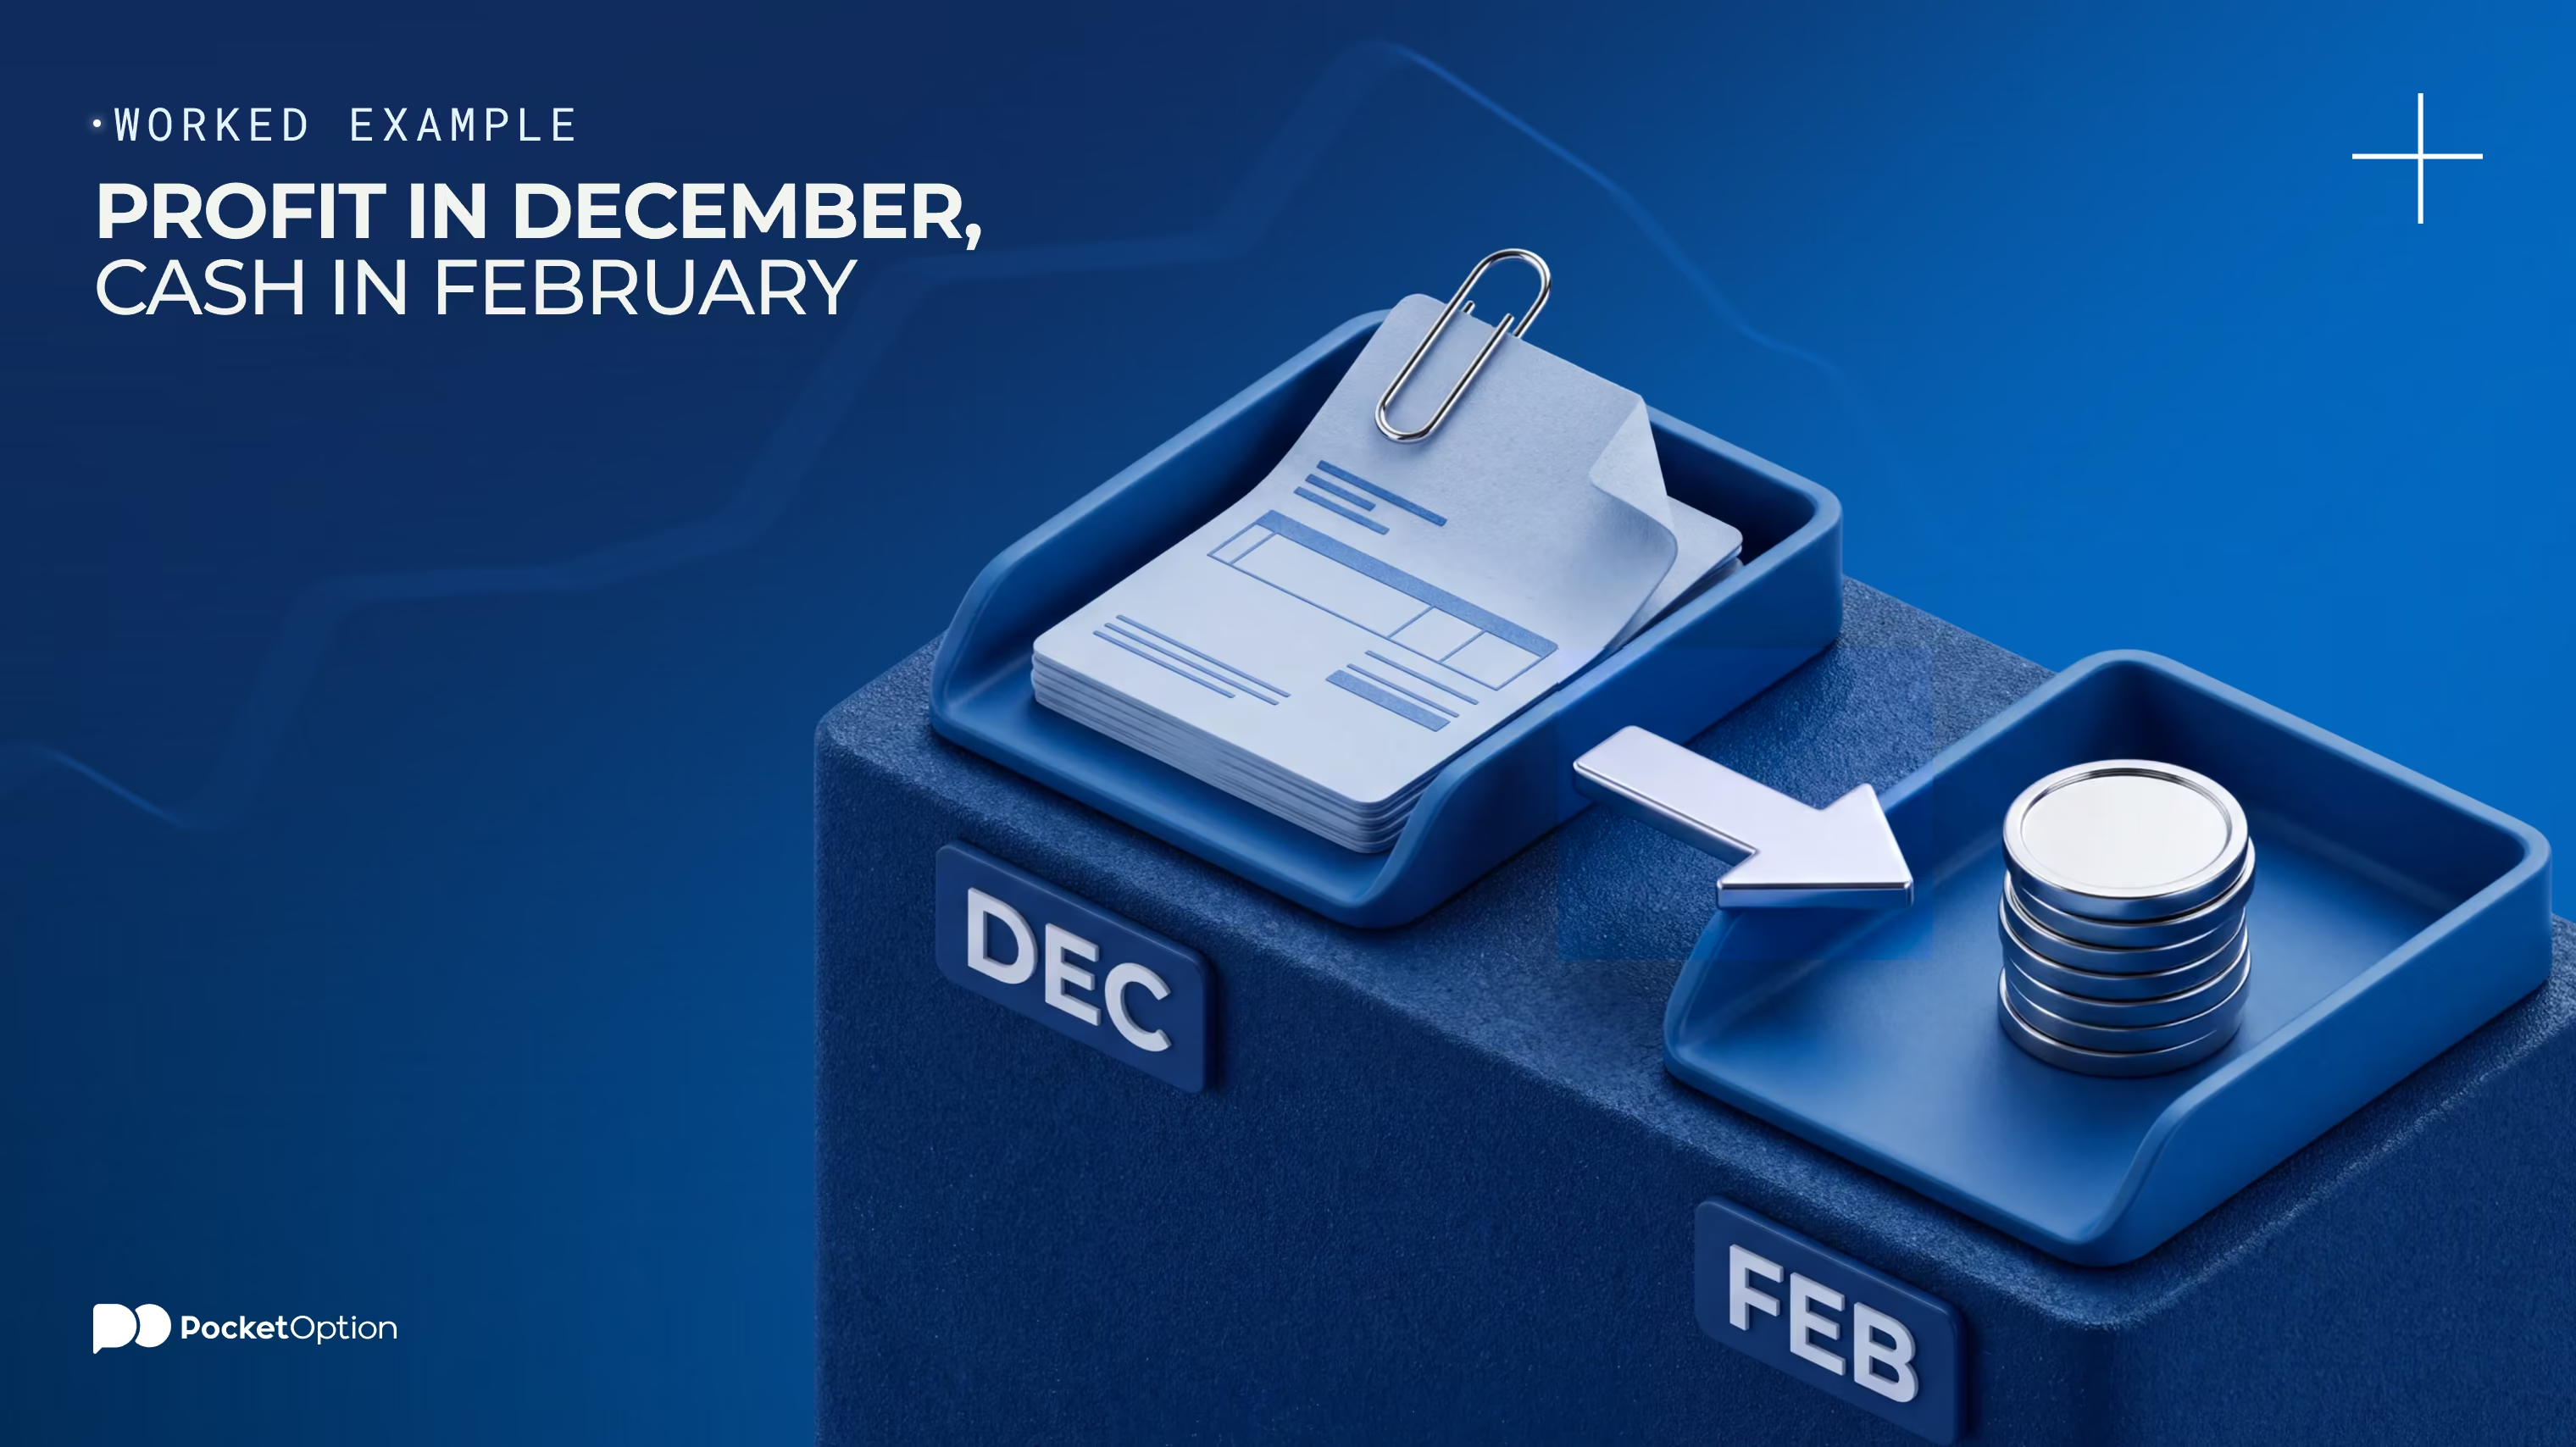
Let us consider the case of a software company selling and installing the software. In December, the company completes the project, delivers it to the client and invoices for $500,000 payable in 60 days. The cost of completion of the project is $300,000, paid in December.
Here is the impact on each financial statement.
Statement | Information on the quarter |
|---|---|
Income statement | Revenue $500,000, cost $300,000, profit $200,000 |
Cash flow statement | Cash outflow $300,000, cash inflow nothing, operating cash flow negative $300,000 |
Balance sheet | Accounts receivable increased by $500,000 |
Both of the first two statements are correct. The company earned $200,000 profit completing the project, and spent $300,000 cash. The difference between the reported profit and the cash flow is $500,000, and is completely represented by one receivable.
Now let us follow the transaction further. In February, the client pays. The cash inflow is increased by $500,000, the receivable becomes zero, and the income statement shows nothing, since the revenue was recognized in December. Now the profit and cash flow are the same, but with one quarter delay.
That is an accrual in accounting working as it should. The December statement shows that the company did $500,000 worth of work. The February cash flow statement shows that the company received the payment. Neither of these statements shows all the facts by itself.
Now imagine that the client does not pay. The revenue was recognized, so the adjustment will come later as a write-off of the bad debt, in a period when nothing went wrong operationally. This is why you need to pay attention to the growing receivable.
Why Financial Statements Traders Read Are Built on Accrual
So what is the accrual method of accounting doing in every financial statement you read? It is there because the alternative would be worse.
According to the US GAAP, and according to the IFRS, accrual accounting is required for the financial statements of publicly held companies. Thus, a company filing with the SEC cannot choose cash basis, and all annual and quarterly reports you read about a public company use accrual accounting.
The reason is consistency. Under the cash basis, a company that happened to collect two large invoices in the last week of the quarter would look transformed, and the same company would look broken in the following quarter when the collections landed elsewhere. The business itself did not change. Accrual accounting eliminates this problem by accounting for the activities, not the payment date.
Also, it allows comparison of two companies on the same terms, whether you trade the stock for one week or ten years. A simple illustration of fundamental analysis of stocks using this approach is available separately.
The price of comparability is judgment. Determining when the revenue is earned, what the lifespan of an asset is, and how much of a receivable may become bad debt are all estimates. These estimates are usually reasonable, but sometimes they are the precise point where the problem hides.
Stock CFDs on the platform
Get StartedAccrual vs Cash Basis: Why the Gap Matters
If you process the same quarter under the two methods, you will receive two different but equally defensible answers.
Accrual basis | Cash basis | |
|---|---|---|
Revenue recognized | Upon delivery | Upon receipt of payment |
Expenses recognized | Upon occurrence | Upon payment |
December quarter in our example | Profit $200,000 | Loss $300,000 |
Shows you | What the business has done | What the business has in the bank |
Used by listed companies | Yes, mandatory | No |
A $500,000 difference on one transaction, with no disagreement about any fact. Both columns describe the same December quarter accurately, yet they answer different questions.
The accrual accounting meaning for traders is a narrow one: the income statement describes the activities of the business and the cash flow statement describes its cash flows.
The difference is important because people read the accrual number and assume that it is the cash number. Reported profit does not pay dividends, service the debt or finance a buyback. Cash does those things, and the two are related without being the same.
Where to See the Gap: Income Statement vs Cash Flow Statement
The useful point about the accrual concept in accounting is that these statements are supposed to illustrate the difference, as long as you read more than one of them.
The cash flow statement reconciles the difference for you. The operating section starts with net income, the accrual number, adds items that never involve cash and makes adjustments for changes in working capital. The result is the operating cash flow. The adjustment lines in the middle of the statement are the difference, stated clearly.
This establishes the order of reading. Take net income from the income statement and operating cash flow from the cash flow statement, then analyze the working capital lines to understand the sources of the difference. Fast growth of receivables tells one story; fast growth of inventory tells another one.
This is as much about sizing as about analysis. If your position is based on reported earnings not yet confirmed by cash flow, then the position should be smaller than one where the two numbers agree. Size your positions for a range of possible outcomes, not just one prediction. It is the same discipline as estimating potential portfolio loss with value at risk.
The Simple Rule: High Accrual Profit, Weak Operating Cash Flow
Here is one rule to remember: over several years, compare net income with operating cash flow and treat a persistent difference as a signal to investigate further and not as the conclusion.
The ratio is operating cash flow divided by net income. A ratio around 1.0 or above over several years suggests that profit is received as cash. If the ratio stays consistently below 1.0, it suggests that the reported earnings are ahead of the cash collections, and you need to understand the reasons for this.
Use the ratios as rough guidelines, not hard thresholds. There is no single number to distinguish between a healthy company and an unhealthy one, and any article promising such a threshold is misleading.
The rule is not just common sense. Richard Sloan's paper in The Accounting Review in 1996, "Do Stock Prices Fully Reflect Information in Accruals and Cash Flows about Future Earnings?", found that firms with high accruals, meaning those where earnings and cash flow differed widely, tended to deliver lower returns than firms with earnings supported by cash flows. The idea was explored a lot after that, including discussion of the reasons for this effect.
But, this research does not provide you with any trading signal. This research points out at a trend that has been identified through many firms across many years. An average trend will not necessarily help you identify what will happen in your own case. So, if you were wondering what is an accrual accounting method real value for traders, here is an honest answer to your question: it raises better questions, not guarantees.
Red Flags That Signal Poor Earnings Quality
One difference is not a problem by itself. These are the patterns that turn it into one.
Receivables are growing faster than revenue, year after year. Revenue is recognized despite the fact that the clients pay slower. One quarter can be noise; the trend over several years is what matters.
Inventory is growing faster than sales. Goods are produced, but not sold, and the write-downs are postponed rather than prevented.
Revenue is growing and operating cash flow is falling. These two tend to move together; if they are diverging for several years, reported growth is not converted into cash.
The profit depends on one-time events every year. If a one-time event occurs every year, then it is not one-time; it is the regular business.
Changes in accounting estimates that happen to increase earnings. Extending the useful life of an asset or reducing the provision for bad debts increases earnings without changing anything real.
Operating cash flow is increased by delays in paying the suppliers. Delaying the payment increases the current cash flow and borrows from the future.
There are also innocent explanations. A fast-growing company has to finance its receivables and inventory, so the lag of operating cash flow behind the profit is the natural sign of growth, not a warning sign. A seasonal company demonstrates the same difference on a predictable cycle. One single big contract can distort one quarter completely and mean nothing.
This is the reason why the test is about persistence, not mere presence. One quarter does not tell you anything. Several years in the same direction tell you something, and the accrual accounting basics discussed above will allow you to analyze what it is.
No special accounting degree is required. If you are not familiar with how companies come to be listed and priced, there is a simple explanation of how the stock market works that goes with this.
Conclusion
Look at the two numbers together, or none of them will make sense.
Net income shows you the earnings of the company under a certain timing system. Operating cash flow shows you the actual collections. Both numbers are correct and audited, and the difference between them is where the most interesting questions lie. Make it a habit: before taking any action on the profit figure from the news, look at the operating cash flow for the same period and for the three or four preceding years. If the numbers are moving together, the earnings are what they appear to be. If they are drifting apart, you have discovered something worth understanding before you trade, not after.
Disclaimer: The article is only for informational purposes and does not contain any investment advice. Financial statements analysis cannot forecast future prices or returns, and accounting numbers refer to the periods which have passed and not to the future ones. Trading is highly speculative and may not suit everyone.
See more:Education