What Is the Taylor Rule? Formula and How It Guides Interest Rate Policy
The Taylor Rule is a formula that suggests a short-term interest rate based on inflation and economic activity. This guide explains the classic 1993 formula, what the inflation gap and output gap mean, why the neutral real rate matters, and how traders can interpret the rule as a reference point rather than a trading signal.
A recipe tells you roughly how much salt to add. It doesn't mean every cook follows it to the gram. Same idea with interest rates. The Taylor Rule hands you a suggested number. Not a command any central bank has to obey.
What Is the Taylor Rule?
The Taylor Rule is a monetary policy rule. Economist John Taylor proposed it in 1993. It estimates a short-term nominal interest rate. Based on inflation and economic activity. The rule shows how a suggested rate might react when inflation drifts from its target. Or when output drifts from its potential level.
One thing matters immediately here. This is a reference point for analyzing policy stance. Not a mandatory instruction a central bank has to follow. Not a precise forecast of the next rate decision either. The formula itself comes later, in the next section.
The Taylor Rule in practice shows up constantly in rate discussions, well before anyone actually runs the calculation themselves.
Create an account and watch rate expectations shift in real time.
Try Demo AccountA formula on a page stays abstract until you watch rates actually move. Seeing how expectations shift around a real rate decision makes the concept concrete fast.
Watching how market expectations shift once an actual rate decision lands explains this far better than reading about it in the abstract. The gap between what a formula suggests and what a central bank actually does becomes visible in real time, not just in theory.
Open a demo trading account and watch rate expectations move on a live chart.
The Taylor Rule Formula Explained
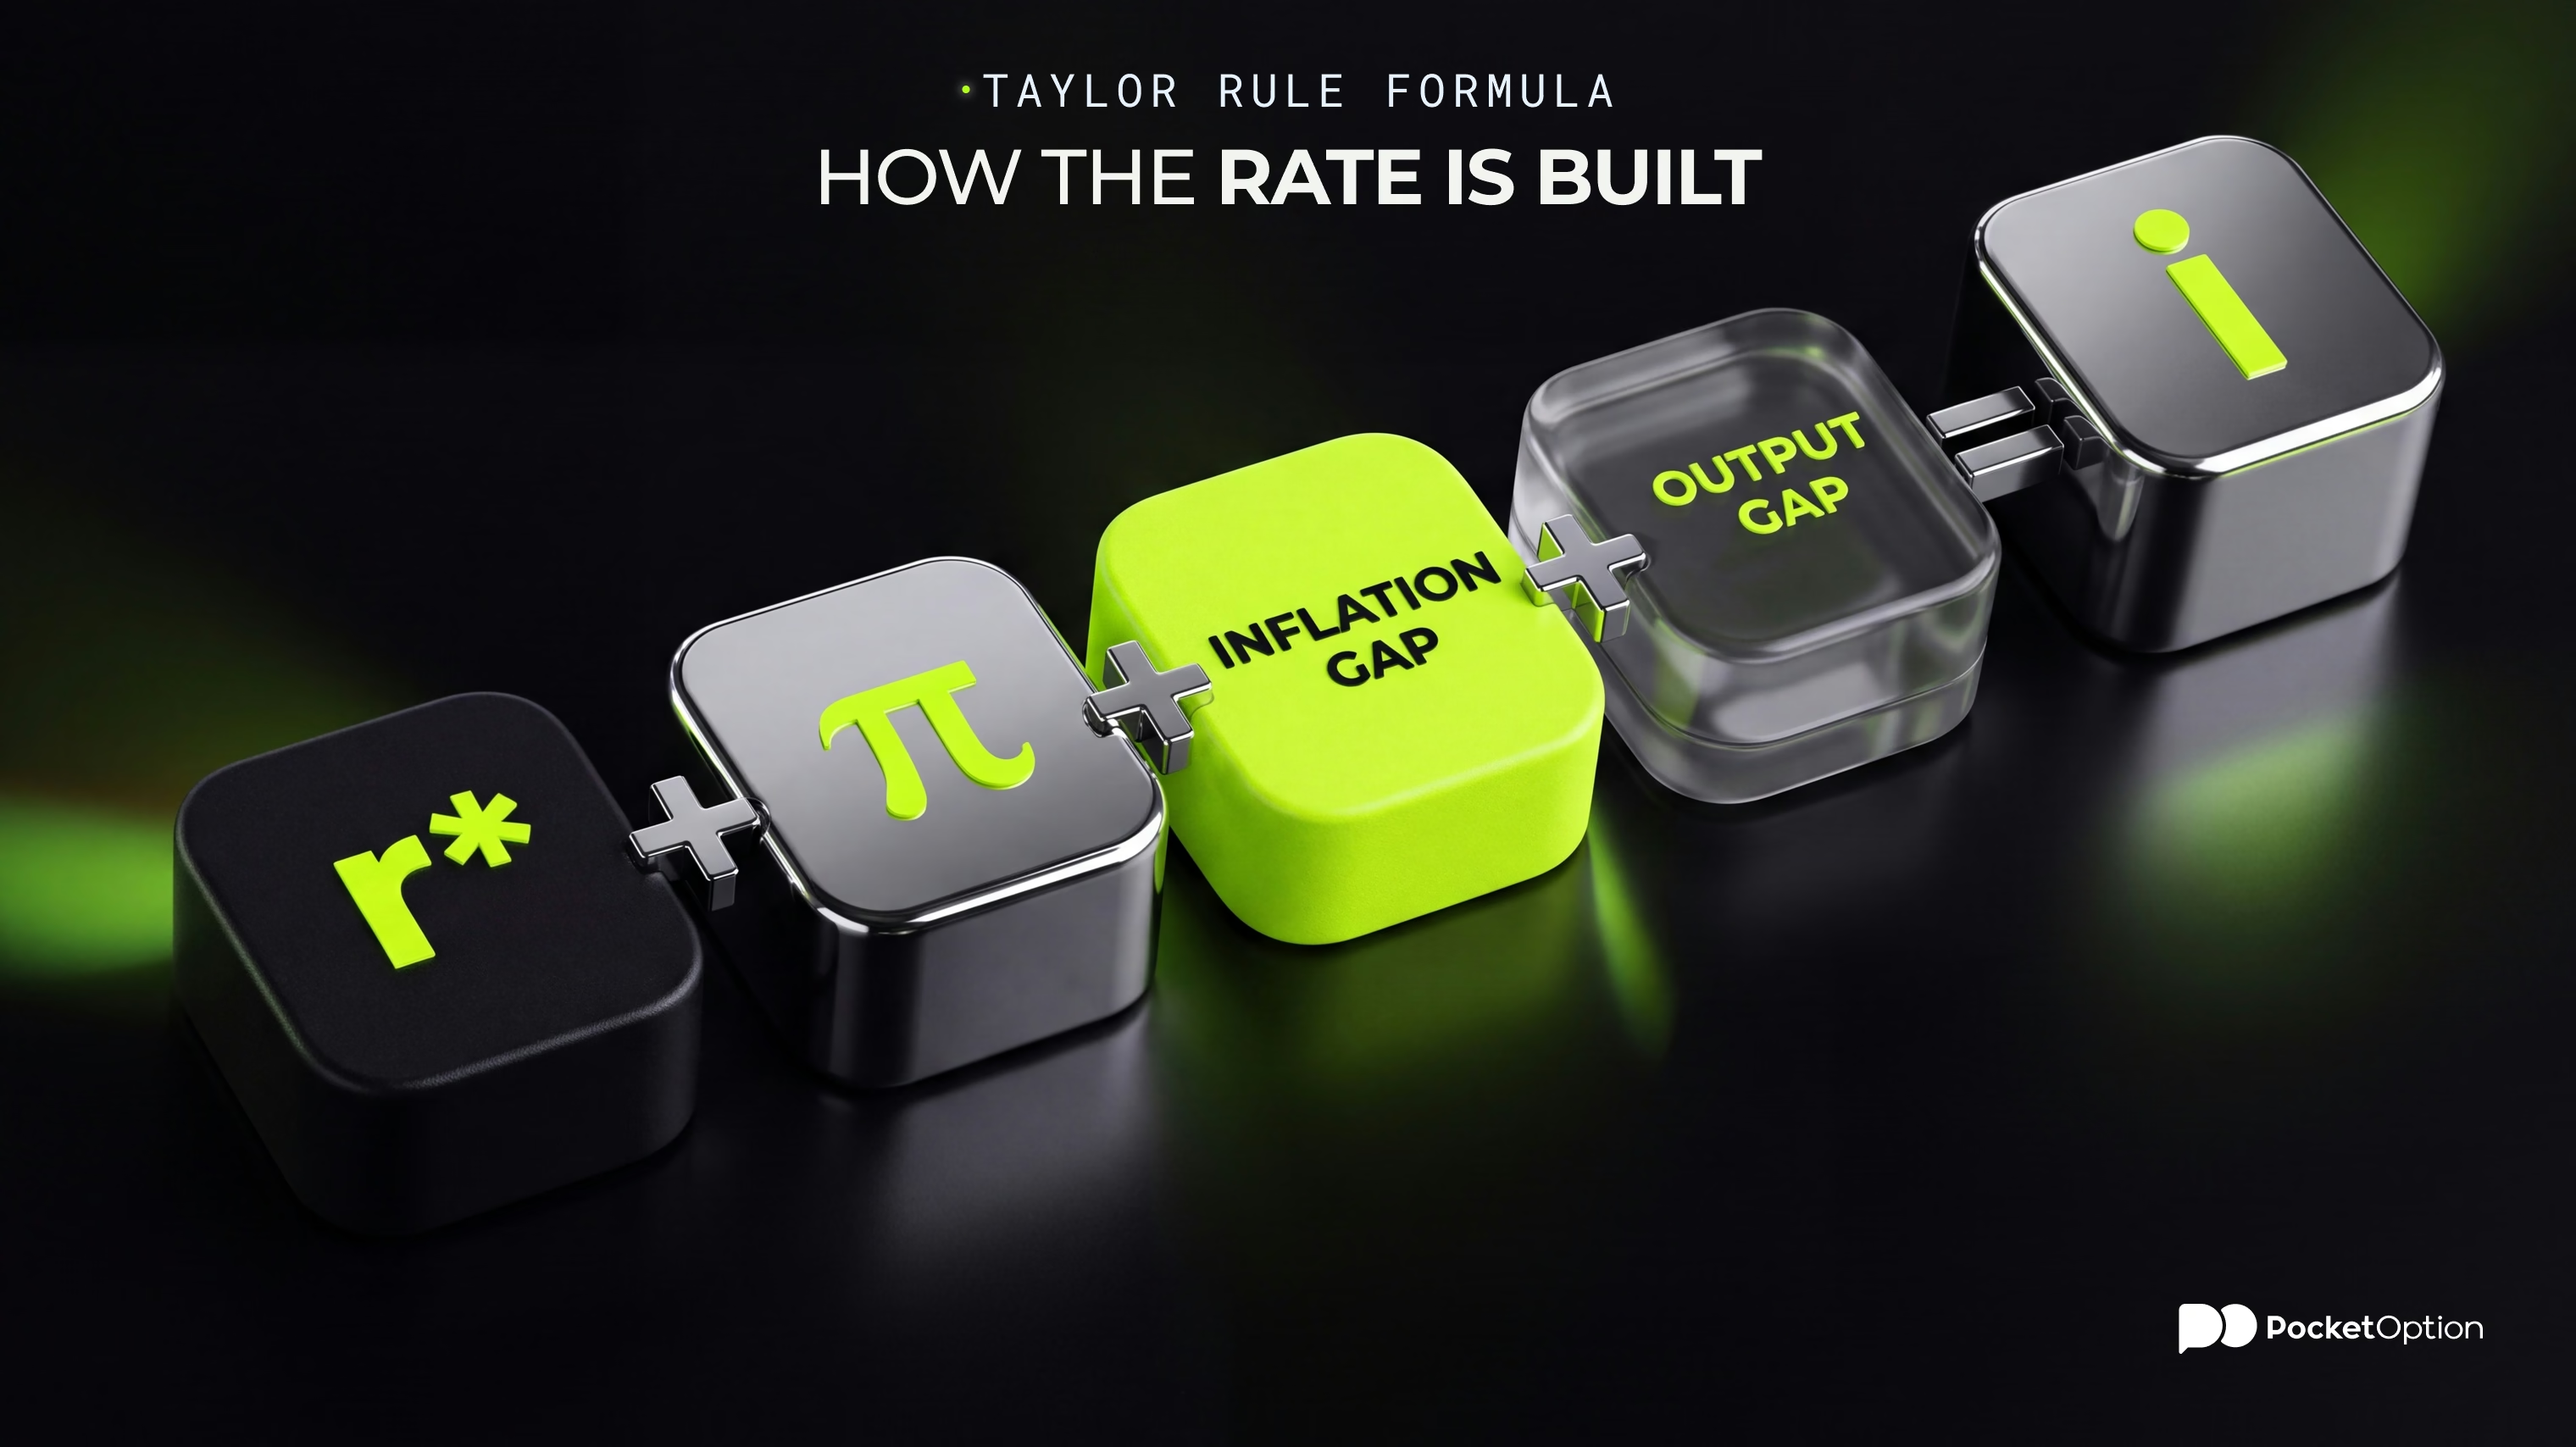
Here's the classic 1993 version, stripped down. i equals r-star plus pi plus 0.5 times the inflation gap plus 0.5 times the output gap. Where i is the suggested nominal policy rate. r-star is the equilibrium, or neutral, real interest rate. Pi is the inflation rate. The inflation gap is actual inflation minus the target. The output gap is actual output minus potential output.
In plain words. The baseline rate starts with the neutral real rate plus current inflation. Then it adjusts. Based on how far inflation sits from target. And how far actual output sits from potential. Positive gaps push the suggested rate higher. Negative gaps pull it lower.
This is the classic taylor rule formula, the 1993 specification specifically. Other versions exist too. Different coefficients. Different inflation measures. Different estimates of potential output. None of that gets covered here in depth, the math stays simple on purpose. A calculated number from this formula isn't some mandatory level the actual policy rate has to hit.
Checking a live pocket option tutorial helps make the abstract numbers feel more concrete.
What the Inflation Gap Means
The inflation gap is simple at its core. Actual inflation minus the inflation target. Run through a basic taylor rule economics example: inflation above target pushes the suggested rate up, all else equal. Inflation below target pulls it down instead.
What the Output Gap Means
The output gap runs on similar logic, different input. Actual economic output minus estimated potential output. A positive output gap means the economy is running above its estimated potential. A negative one means it's running below. What is the taylor rule actually measuring here, in part: how far the real economy sits from a level nobody can observe directly. Potential output is an estimate. Different assumptions about it produce entirely different results.
Why the Neutral Real Rate Matters
r-star plays a specific role here. The equilibrium, or neutral, real interest rate. Roughly, a real rate level consistent with an economy running near potential and inflation staying stable. The classic 1993 rule used 2%. Modern estimates of the neutral rate can differ quite a bit from that figure. The neutral rate itself is an uncertain estimate, not some fixed modern number.
How the Taylor Rule Changes as the Economy Changes
A few simple scenarios show the mechanics directly, without repeating the same definitions again.
Economic Condition | Effect in the Formula | Typical Effect on Suggested Rate |
|---|---|---|
Inflation above target | Positive inflation gap | Pushes the rate higher |
Inflation below target | Negative inflation gap | Pushes the rate lower |
Positive output gap | Economy above potential | Pushes the rate higher |
Negative output gap | Economy below potential | Pushes the rate lower |
Both gaps near zero | Minimal adjustment | Rate stays close to r-star plus inflation |
All else equal, higher inflation gaps or positive output gaps push the calculated rate up. Negative gaps pull it down instead. This isn't a fixed prediction of where a central bank's actual rate will land.
What Does the Taylor Rule Tell Us About Interest Rates?
The result functions as a benchmark. Compare the calculated Taylor rate against the actual policy rate. See whether the real rate sits above or below the level this particular version of the rule suggests.
That gap isn't automatic proof of anything, though. A higher calculated rate doesn't automatically mean policy is "too loose." A lower one doesn't automatically mean "too tight" either. The result depends entirely on which inflation measure got used. Which output-gap estimate. Which neutral rate. Which coefficients. Change any of those inputs and the benchmark shifts too.
Why Economists Use Different Versions of the Taylor Rule
No single, unchanging version of this calculation exists. Different versions use different coefficients on the output gap. Different inflation measures. Different estimates of potential output or the neutral rate. Some add interest-rate smoothing on top.
The 1999 Taylor variation is one example, among several. It leans harder on the output gap than the original 1993 version did. The specific formula isn't worth dissecting here. The bigger point matters more: different assumptions produce different suggested rates. Talking about Taylor-type rules, plural, or a range of estimates, fits the reality better than treating any single number as settled.
Limits of the Taylor Rule
A handful of real limitations deserve attention here, without wandering into a broader monetary policy lecture. What can actually change this kind of estimate:
Choice of inflation measure
Estimate of potential output
Estimate of the neutral real rate
Coefficients used in the rule
Data revisions
Unusual economic conditions
Output gap and neutral rate aren't directly observable. Both get revised over time as new data arrives. A simple formula like this also skips over financial, institutional, and risk considerations that an actual central bank weighs. Schwab describes it as a guidepost, an input. Not an ironclad mechanism.
How Traders Can Interpret the Taylor Rule
The practical value here doesn't require turning a formula into a trading strategy. It helps connect inflation, economic slack, and an interest-rate benchmark. Comparing a calculated rate against the actual policy rate, or against market expectations, becomes more meaningful once the mechanics make sense.
One thing worth stressing. This calculation isn't a standalone forecast of a Fed decision. Or bond yields. Or the dollar. Or stock prices. Markets price in expectations, incoming data, central-bank communication, and plenty of other factors at the same time. A scheme like "Taylor rate above Fed rate equals buy the dollar" oversimplifies badly. That's not how any of this actually works.
Risk Disclaimer: Trading involves significant risk of capital loss. This article is for educational purposes only and does not constitute financial advice. Always conduct independent research and consider your risk tolerance before making any trading decisions.
See more:Education