What Is Quantitative Tightening (QT) and How Does It Affect Financial Markets?
Quantitative tightening shrinks a central bank's balance sheet through runoff and, in some cases, active sales. This guide explains how QT works, how it differs from QE and rate hikes, how it can affect bonds, currencies and stocks, and why its market impact varies.

Picture a landlord who bought dozens of apartments to prop up a struggling neighborhood. Years later, whenever a lease ends, he stops re-letting the unit. No speech. No announcement party. The portfolio just gets smaller, month after month. That slow shrinking is roughly what quantitative tightening looks like on a central bank's books. Sounds dull, right? Markets watch it closely anyway.
What Is Quantitative Tightening?
Quantitative tightening, or QT, is a central bank shrinking the assets on its balance sheet after a stretch of buying them. We're talking mostly government bonds and similar securities, piled up during quantitative easing, or QE. The shrinking happens in two ways. Stop reinvesting the money that comes back when securities mature, and holdings fall on their own. Or, where a central bank uses that tool, sell some securities outright.
One point before anything else. Quantitative tightening is balance-sheet policy. It isn't just another name for a rate hike. A rate hike changes the price of short-term money. QT changes how many securities, and how many reserves, sit in the system. Different lever, different channel.
Open a demo account and follow how markets react to central bank news, with virtual funds.
Try Demo AccountBalance-sheet charts look calm. Prices rarely do.
Balance-sheet news usually arrives quietly, a line in a statement or a mention in the minutes, and the market's reaction can unfold over hours or weeks. Following a few rate-sensitive instruments through that kind of news on a demo account shows how differently the same headline can land, with virtual funds in place of real money.
Opening a demo trading account lets you run that experiment before risking anything real.
How Quantitative Tightening Reduces a Central Bank's Balance Sheet
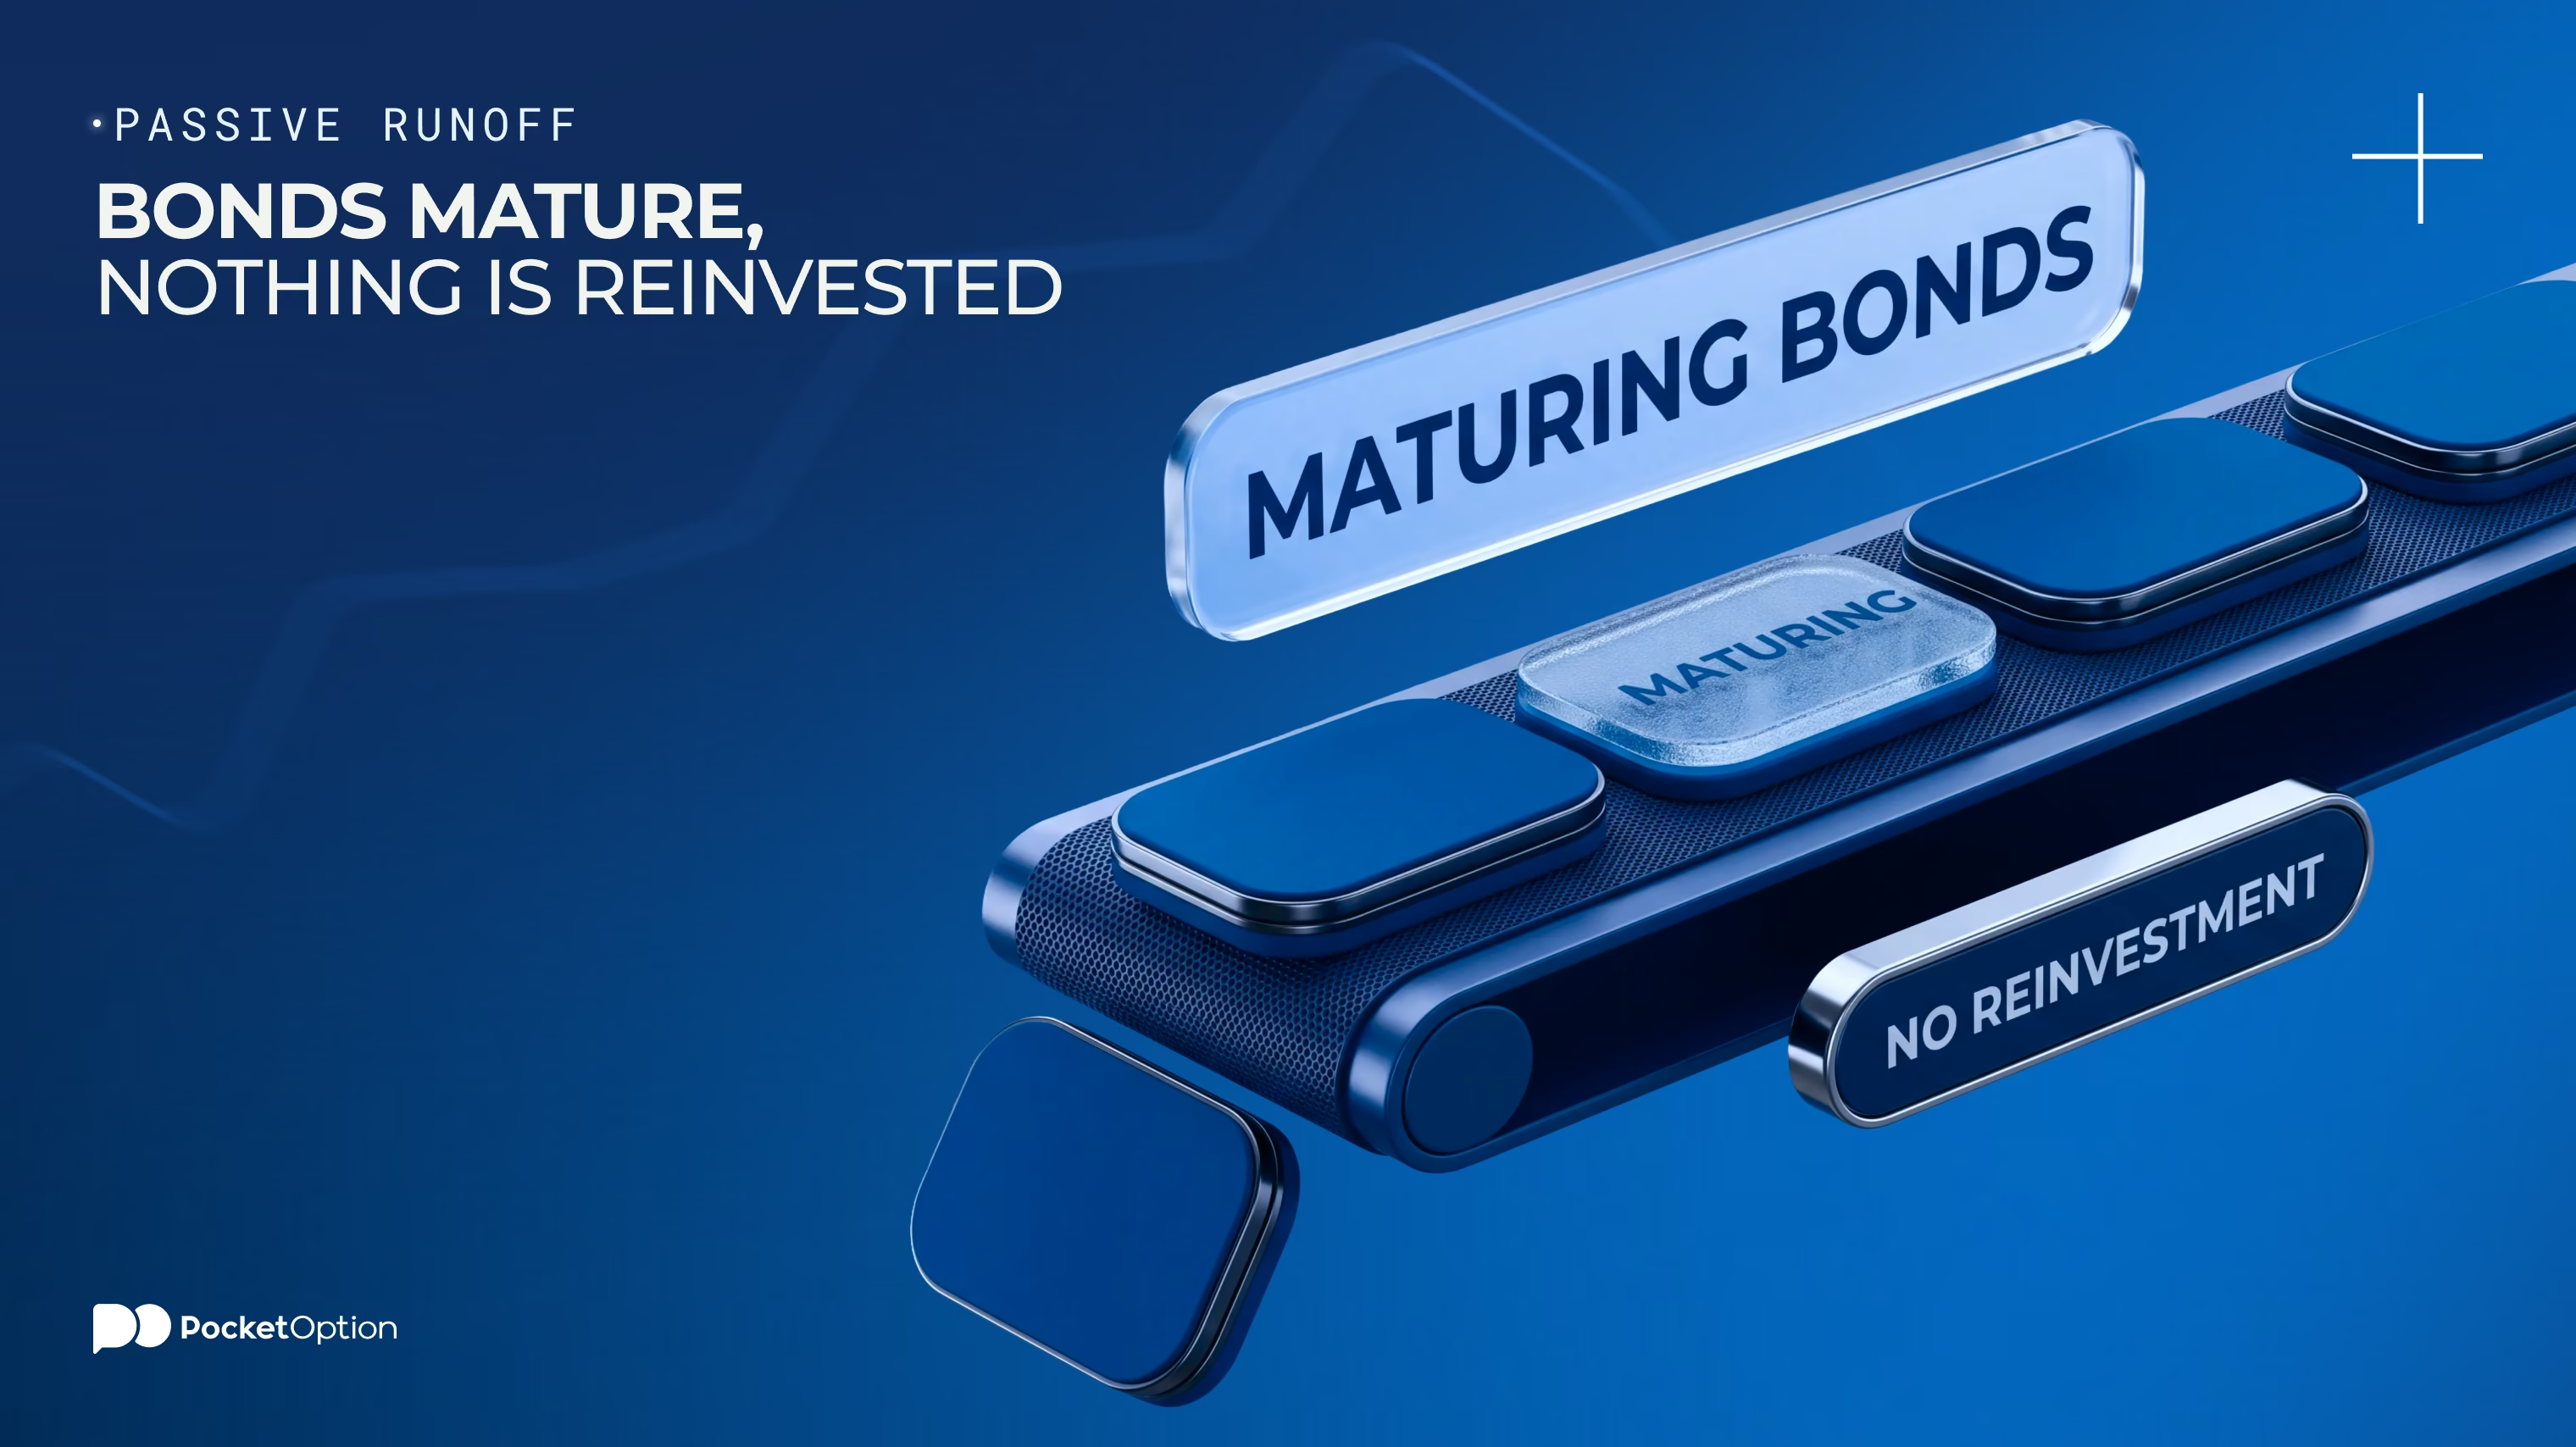
So what is quantitative tightening changing on the books, exactly? Start with the asset side. A central bank holding a bond gets principal back when that bond matures. Before QT, that money usually went straight into new bonds. Under QT, less of it gets reinvested, or none. Holdings shrink without a single sale.
Following a line item from asset to reserve is easier with a chart open next to it. If you haven't set up your workspace yet, the pocket option tutorial walks through it step by step.
Some central banks add active sales on top, selling part of their securities to the market before maturity. Others never do. Either way, the asset side moves in one direction. Fewer securities.
Now flip the ledger. Securities are assets. Reserves held by commercial banks are a liability of the central bank. When assets shrink, reserve balances, or other matching liabilities, usually shrink too. Usually. It's not a clean one-for-one rule, and a dollar of runoff doesn't always take a dollar out of broad money or lending.
What is quantitative tightening, in one line? A slow, scheduled reduction in the securities a central bank holds, with knock-on effects for reserves. Mostly bookkeeping, done gradually, in the background.
Passive Runoff vs Active Asset Sales
Ask three central banks about the quantitative tightening meaning and you can get three slightly different answers, because each mixes the tools its own way. Start with passive runoff. Bonds mature, the money isn't fully reinvested, and holdings shrink on their own schedule. Back to the landlord: leases simply end. Active sales are the other tool. The central bank sells securities before they mature. That's the landlord selling the building early. Some use only runoff. Others combine both. QT doesn't have to include sales at all.
What Happens to Bank Reserves During QT
Reserves live on the liability side. Securities live on the asset side. Shrink the second and the first can drop too. Does that matter? Absolutely. Banks use reserves to settle payments, and the central bank leans on them to keep short-term rates where it wants them. So as reserves approach a level the central bank is happy with, it may slow runoff or stop it. A deliberate call, not an accident.
Quantitative Tightening vs Quantitative Easing
QE and QT point in opposite directions. QE expands a central bank's holdings through asset purchases. QT reduces them through runoff, sales, or both. A table shows the contrast better than a paragraph would.
Feature | QE | QT |
|---|---|---|
Balance-sheet direction | Expands | Shrinks |
Asset purchases and holdings | Buys securities, so holdings rise | Holdings fall through runoff and/or sales |
Effect on reserves and liquidity | Adds reserves and liquidity | Drains reserves over time |
Typical effect on long-term yields and financial conditions | Can press long-term yields lower and ease conditions | Can nudge long-term yields higher and tighten conditions |
Policy purpose | Support the economy and ease conditions | Withdraw earlier support and normalize the balance sheet |
Implementation | Asset purchases announced as a program | Reduced reinvestment, sometimes with sales |
Opposite direction, sure. Opposite impact of the same size? Don't assume it. Buying and pausing purchases hit markets differently, and expectations plus what's already priced in change the picture. Read the table as a map of mechanics, nothing about size.
Quantitative Tightening vs Interest Rate Hikes
Two different tools. A rate hike lifts the short-term policy rate, and overnight borrowing costs follow almost immediately. QT works on the balance sheet instead: its size, its mix, and with them the supply of reserves and of securities held by the public. Think liquidity and longer-term financial conditions, not the overnight rate.
Here's the part people miss. A central bank can raise or cut rates while QT keeps running, or while it's paused. Separate dials. Still, they aren't fully independent. Both end up in the same place, overall financial conditions, and they can reinforce each other or cancel out.
How QT Can Affect Bond Markets
Think supply and demand. With less central bank demand, or more bonds returning to private hands, investors have to absorb extra duration. That can push longer-term yields up and bond prices down, especially if the change wasn't fully priced in.
Can. Not will. Yields also respond to inflation expectations, the growth outlook, rate expectations, Treasury issuance and general risk sentiment. When QT is well telegraphed, its effect can be hard to isolate. So a blanket rule that QT always lifts yields doesn't hold up.
How QT Can Affect Currencies and Stocks
Take currencies first. Tighter financial conditions can lend a currency some support, and so can shifting rate and liquidity expectations. But FX is a crowded room. Relative monetary policy, growth, inflation and risk sentiment all talk at once, and one voice rarely decides the move.
Stocks come through a different door. Thinner liquidity and higher yields can weigh on valuations, especially for long-duration assets, the ones whose profits sit far in the future. Then earnings, growth hopes and positioning wander in and change the reaction. Same trigger, different outcome.
Why the Market Impact of QT Can Vary
Why doesn't every QT cycle hit markets the same way? Because the setting changes each time. What can change the market impact of QT:
Pace of runoff
Passive runoff versus active sales
Level of bank reserves
Government bond issuance
Policy-rate path
Market expectations and pricing
Liquidity conditions
Broader macro environment
A gradual runoff announced well in advance may carry a smaller marginal impact than a surprise acceleration or active sales. Surprise matters. And there's no universal runoff threshold past which the market must react. Anyone quoting one is guessing.
When and Why Central Banks Slow or Stop QT
The goal usually isn't a balance sheet of zero. Central banks decide what operating framework they want, then figure out how many reserves money markets need to function and policy needs to work smoothly. As reserves drop, slowing runoff, or stopping it, helps avoid a slide from ample liquidity into scarce conditions.
Pace, caps and dates shift over time, and they differ from one central bank to another. For current figures, go to the central bank's own website. A number frozen into an article goes stale fast.
What Traders Should Watch During Quantitative Tightening
Build a routine, not a hunch. What to monitor during QT:
Pace of balance-sheet runoff
Reinvestment policy and caps, where they apply
Level of bank reserves
Government bond yields and term premium
Money-market liquidity and stress
Policy-rate expectations
Whether the QT pace changes relative to prior guidance
QT is one input among many in market pricing. Alone, it won't give you a dependable signal for bonds, currencies, stocks or indices. And nothing on that list is a trade idea.
Risk Disclaimer: Trading involves significant risk of capital loss. This article is for educational purposes only and does not constitute financial advice. Always conduct independent research and consider your risk tolerance before making any trading decisions.
See more:Education